Photography Studio Booking Deposits Cleanup.
Getting booking deposits back on track for a photography studio
Company Overview:
- Owner-operated service business experiencing reconciliation issues with booking deposits
- Photography studio business
- British Columbia, Canada
Improved sales and deposit oversight
10s of thousands of dollars in sales tax obligations cleared
Better SOPs for tracking sales deposits
The bookkeeping challenge
A photography business in British Columbia was having issues tracking their booking deposits properly.
Booking deposits were recorded as liabilities; however, there was no oversight as to when the booking deposits were converted into sales, refunded to the clients, or forfeited. As a result, the booking deposit liability accounts kept accumulating funds.
It was also unclear which of these funds were reported as sales and charged the appropriate sales tax.
Objectives:
- Accurately calculate bookkeeping deposits
- Calculate booking deposits converted to sales
- Find the sales tax amount on converted booking deposit sales and file sales tax
- Come up with a plan to handle bookkeeping deposits moving forward
Accurately calculate bookkeeping deposits
The cutoff date was selected, and we got the following documents – deposit ledger, booking calendar, signed contracts, invoices, payment processor reports, and the bank statement. After that, we traced the old transactions to the actual booking and validated the initial balance before applying it in our process of reconciliation.
Afterwards, we created an invoice number for each booking and correlated the receipts, applications, refunds, and forfeitures to the invoice number. The deposits were recorded in their gross form in relation to the payments made by the clients, while processing fees were separately tracked and the net payout was correlated with the bank.
Illustrative deposit reconciliation
| Movement in the deposit account | Amount |
| Verified opening deposit balance | $4,000 |
| Add new deposits received | $5,500 |
| Less deposits applied to invoices | ($4,200) |
| Less unused deposits refunded | ($800) |
| Less deposits forfeited at gross value | ($525) |
| Closing liability supported by open bookings | $3,975 |
We matched the balance reconciled to the booking register and the adjusted the general ledger.
Calculate Bookkeeping Deposits That Should Be Converted to Sales
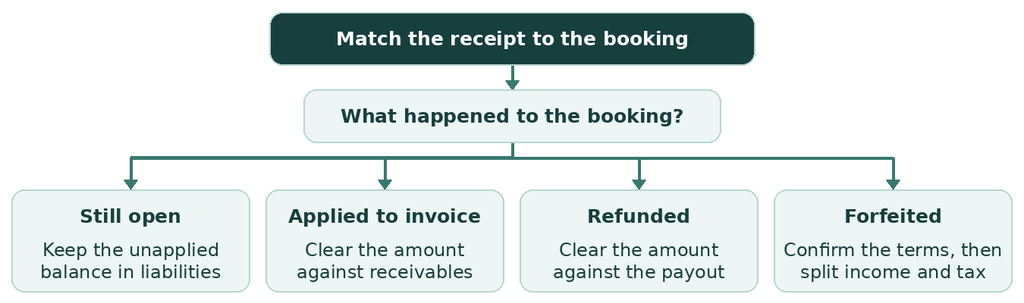
We correlated the booking status with its original invoice. In case the shoot was done, we would see whether the money had been booked. If there was an existing final invoice, we would make the deposit payment against it and would not book it twice.
How we cleared the balance
In case the sales were not yet booked for the completed shoot, we would book both the entire earned revenue and tax against the invoice. We would debit the liability deposit and credit the sales deposit.
If we confirmed the refund of unused deposit, we would debit the deposit liability and credit the clearing account of the bank/processor. For the missed shoots, we would keep the deposit and transfer it to the sales account.
In case of cancellation, we would look at the contract and see how much and when the deposit could be withheld. We would clear the gross amount from the liability and would separately book any applicable tax.
Find the Sales Tax Amount on Converted Booking Deposit Sales and File Sales Tax
With genuine deposits, we considered the date of application or forfeiture of the deposit. With advance payments, we considered the date of payment or the date on which the payment fell due. We examined invoices and contracts, because the tax reporting date might not have been the same as the recording of revenue.
Completed booking with digital delivery
With the digital-only offering, we recognized sales of $3,000, and GST of $150 at 5%. We netted the $600 deposit against the $3,150 invoice to arrive at $2,550 owing. We verified that the GST had been reported only once in the tax reports.
Packages with prints and cancelled bookings
B.C. PST was handled separately. With the digital-only package in our example, there was no PST. However, if there was a package selling for $3,000 with mandatory prints or an album and a 7% PST rate, we would calculate $210 based on the total price without considering the deposit. Where customers could purchase prints as a separately priced offering, we examined PST in relation to the PST charge on such items.
The $525 forfeiture met the GST conditions under the forfeiture ruling of the federal government, and we treated the amount as being GST inclusive. Thus, we reported $25 in GST ($525 × 5/105) and $500 as cancellation income. We handled the PST separately in the case of cancellations with taxable goods or fees.
How we prepared the returns
The modifications were categorized according to the filing period. In addition, GST and PST were tied to their respective ledger accounts and reconciled against previous tax filings. Our filing strategy provided for client authorization prior to filing GST/HST through the Canada Revenue Agency and PST through eTaxBC, in addition to any remittances, saving confirmations and adjustment requests in relation to past filed periods.
Come Up With a Plan to Handle Booking Deposits Moving Forward
Our system for QuickBooks Online provided for a single booking liability account for deposits. Every invoice would provide the total payment for the shoot as well as how the deposit was removed from the invoice through either forfeiture or a refund.
At booking
Our contract language would be consistent in relation to deposit, advance payments, refunds, and rescheduling. Separate items were created within the invoices for the digital packages and the physical products. The process checklist would include receiving an original receipt of the deposit, a booking in the liability account as well as posting to the bank and/or payment processor.
When a booking changes
The client was to provide us with a weekly checklist verifying complete bookings, cancelled and rescheduled bookings and attaching the invoice or refund/cancellation. We were responsible for maintaining the register and making the posting for that invoice. In case of a booking cancellation, we were to highlight unclear terms for the client to verify.
At month end
A new monthly procedure was created which linked the booking register with the liability account in addition to highlighting all deposits booked for past shoot dates, all the unmatched payments and credits in completely paid invoices. We also added a filing verification procedure verifying taxable invoices/credits/forfeitures for the correct period and occurrence.
At a Glance
Business type
Photography business
Support Provided
Quickbooks bookkeeping cleanup, reconciliation, sales tax filing, monthly bookkeeping
How we worked together
Fully remote
Bookkeeping Professional
Samuel, Owner, Paperless Books
Facing a similar situation? Let’s solve it together.
Need Monthly Bookkeeping Services?
Paperless Books provides remote bookkeeping support for Canadian businesses.